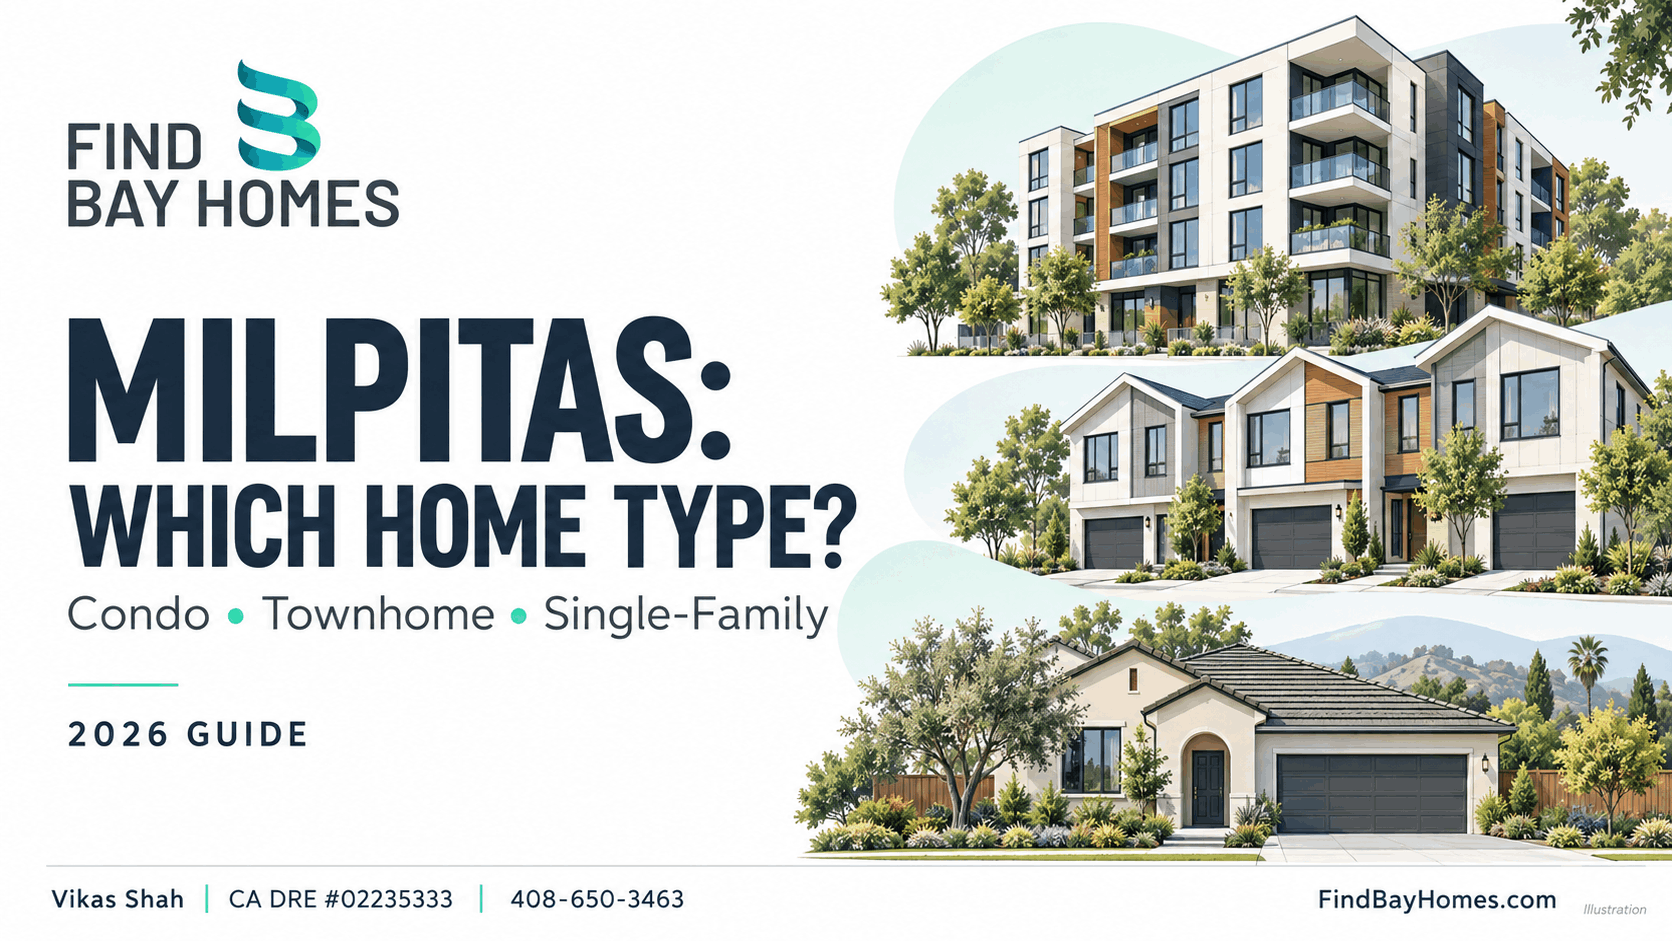
Which property type should you buy in Milpitas? Compare the total monthly cost, ownership documents, maintenance responsibilities and layout—not just the asking price. A condo may reduce some individual maintenance tasks, a townhome may offer a multi-level layout, and a detached house may offer more separation and outdoor space. None is automatically the best financial choice.
Updated September 14, 2026. Examples below are planning scenarios, not current listings or loan quotes.
First separate building style from legal ownership
“Townhome” often describes a building’s style. It does not, by itself, establish what land or structures you own or who maintains them. A townhome can have condominium ownership or a different legal structure. A detached home can also be part of an association. Read the title information, governing documents and maintenance obligations for the actual property.
The California Department of Real Estate’s August 2026 guidance explains why common-interest development documents deserve careful review. Understand the CC&Rs, rules, association financial information and known issues before deciding to buy.
Compare the practical tradeoffs
- Condo: check shared entrances, elevators, parking rights, storage, noise transmission and the association’s responsibility for major components.
- Townhome: test stairs, bedroom separation, garage access and outdoor space. Confirm exterior and roof maintenance instead of assuming the HOA covers them.
- Detached house: inspect the roof, drainage, landscaping and other systems you may maintain yourself. More separation does not eliminate rules, easements or repair costs.
Tour with your actual routine in mind. Where will groceries come in? Can the layout support working from home? Is parking deeded, assigned or subject to rules? Could the stairs become inconvenient? These details can matter more than a broad property-type label.
Compare total cost, including costs outside the mortgage
Build a worksheet for each candidate: principal and interest, property taxes, insurance, HOA dues, utilities, maintenance and reserves. Include any known special assessment and investigate likely upcoming projects. Do not count HOA-covered services twice, but do not assume dues cover everything.
Consider two hypothetical homes with the same loan payment. One has $550 monthly HOA dues and the other has no dues but requires you to fund roof, exterior and yard work directly. The $550 is not automatically wasted, and the no-HOA property is not automatically cheaper. Compare the actual services, future obligations and condition.
Use the Find Bay Homes mortgage calculator to compare financing assumptions, then add any expenses the calculator does not include. Replace default values with property-specific estimates. See our Milpitas income and affordability guide for broader budget planning.
HOA questions to resolve before committing
- What does the association maintain, and what remains your responsibility?
- What do the budget, reserve study and financial statements show?
- Are assessments, litigation, insurance changes or major repairs disclosed?
- What rules apply to rentals, pets, parking, alterations and use of common areas?
- Are meeting minutes consistent with the other disclosures?
- Has your lender reviewed the project and identified any financing conditions?
Ask for clarification where records disagree. The DRE’s homeowners association resources include reserve-study and operating-cost guidance. A low monthly assessment alone does not establish that an association is financially healthy.
Insurance and financing need property-specific answers
Ask an insurance professional to explain the master policy and the coverage you need individually, including relevant deductibles and exclusions. Obtain a lender’s assessment of the actual property and project early. Approval of your personal finances does not automatically approve a condominium project.
For every property type, use an independent inspection and appropriate specialist follow-up. The Bay Area inspection guide helps you distinguish unit-level conditions from broader questions.
Frequently asked questions
Is a Milpitas condo always cheaper than a house?
Not on an all-in basis. Compare purchase price, financing, dues, insurance, taxes and maintenance for the specific homes.
Does a townhome owner own the land?
The style label does not answer that. Verify the legal ownership and boundaries in the title and governing documents.
Does no HOA mean no restrictions?
No. Local rules, recorded restrictions and easements may still apply. Investigate your intended uses and alterations.
Which type is best for resale?
Resale depends on the specific property, condition, location, costs and market at the time. No property type guarantees appreciation or a fast sale.
Build a shortlist around your priorities
Start with the Milpitas buyer guide. Bring Vikas two or three candidate homes and your monthly budget so the comparison can focus on actual obligations and daily use.
Vikas Shah | CA DRE #02235333
Find Bay Homes | Doorlight Inc. | Brokerage DRE #02219383
Call 408-650-3463 or vikas@findbayhomes.com.
More Milpitas planning guides
FROM OUR BLOG
Top Mistakes Home Buyers Make in Milpitas — and How to Avoid Them
The most consequential buying mistakes often happen before an offer is signed: using an incomplete budget, assuming a home fits your daily needs, and committing before unresolved property or contract questions are understood. A better Milpitas buying process gives each question an owner, a source an
Milpitas New Construction Guide: What Buyers Should Know Before Purchasing
Buying new construction in Milpitas means evaluating the finished home, the builder’s contract and the development together. Before committing, confirm exactly what the price includes, compare financing offers, review the applicable subdivision disclosures and HOA budget, and establish how inspectio
What Can You Buy in Milpitas for $1 Million, $1.5 Million & $2 Million?
What can $1 million, $1.5 million or $2 million buy in Milpitas? Each budget creates a different shortlist, but none guarantees a particular bedroom count, neighborhood or condition. At $1 million, investigate attached homes and any smaller or condition-sensitive options that fit. At $1.5 million, c